
The audiobook and its companion material, revised for 2026. The complete book read aloud, plus the charts, tables, cast of characters and glossary from the printed edition. Everything here is free. There is nothing to fill in and nothing to sign up for.
Throughout the book, the same six people return. They are entirely fictional, invented to make abstract rules concrete, but the situations they face are drawn from the kinds of conversations financial advisors have every week. This page is here to turn back to whenever it is hard to keep track of who is who.
Audiobook
The whole book read aloud, free: 24 tracks, 5 hours 41 minutes. Play any chapter here, or download it to listen offline. Narrated with a synthetic voice.
- Opening Credits0:59Download
- Introduction: Why I Wrote This Book5:05Download
- Cast of Characters5:38Download
- Chapter 1: The Real Risk Isn’t the Market6:36Download
- Chapter 2: Sequence of Returns — The Risk No One Warns About14:43Download
- Chapter 3: The Volatility Buffer14:14Download
- Chapter 4: Social Security 10121:39Download
- Chapter 5: Claiming Strategies — When to Start and Why It’s (Mostly) Irreversible37:21Download
- Chapter 6: Medicare — Four Parts, Two Paths, and One Hard Deadline19:43Download
- Chapter 7: Part D — Drug Coverage, the New Ceiling, and the Mistakes That Cost the Most19:16Download
- Chapter 8: Beyond the Premium — IRMAA, Long-Term Care, and Medicare’s Gaps21:23Download
- Chapter 9: Required Minimum Distributions — The IRS Wants Its Money19:10Download
- Chapter 10: Roth Conversions — Paying Taxes on Your Terms29:40Download
- Chapter 11: The Case for a Bond Alternative14:57Download
- Chapter 12: How a Fixed Indexed Annuity Actually Works22:51Download
- Chapter 13: Indexed Universal Life — Tax-Free Income and Legacy Planning22:08Download
- Chapter 14: Tax Mitigation in Retirement — Building a Multi-Year Plan18:15Download
- Chapter 15: Generational Wealth Transfer17:59Download
- Chapter 16: Putting It All Together15:53Download
- Important Notice2:51Download
- Glossary7:10Download
- Sources and Where to Verify the Numbers2:37Download
- About the Author0:32Download
- Closing Credits0:22Download
Charts
Seventeen figures from the printed book, in chapter order.
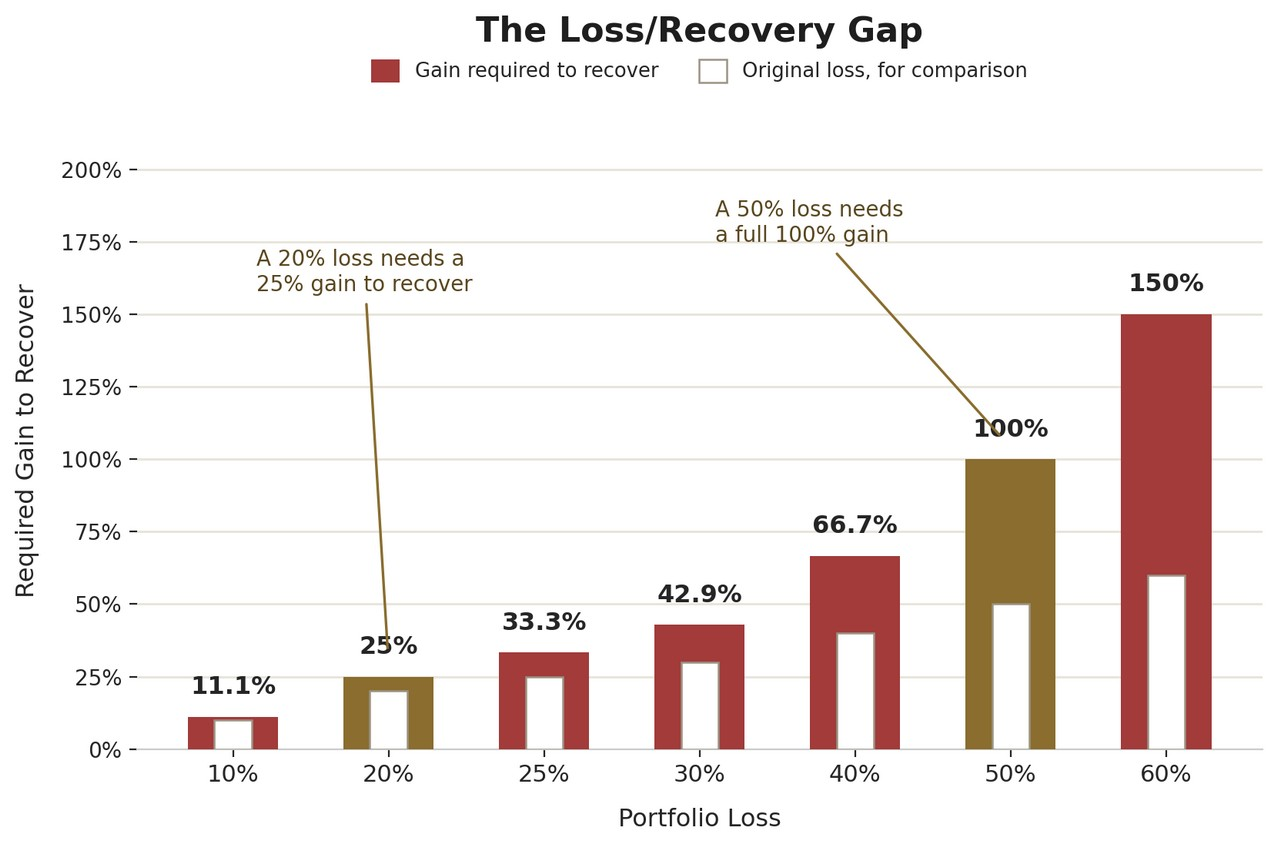
Chapter 2 — Sequence of Returns
Chapter 3 — The Volatility Buffer
Chapter 5 — Claiming Strategies
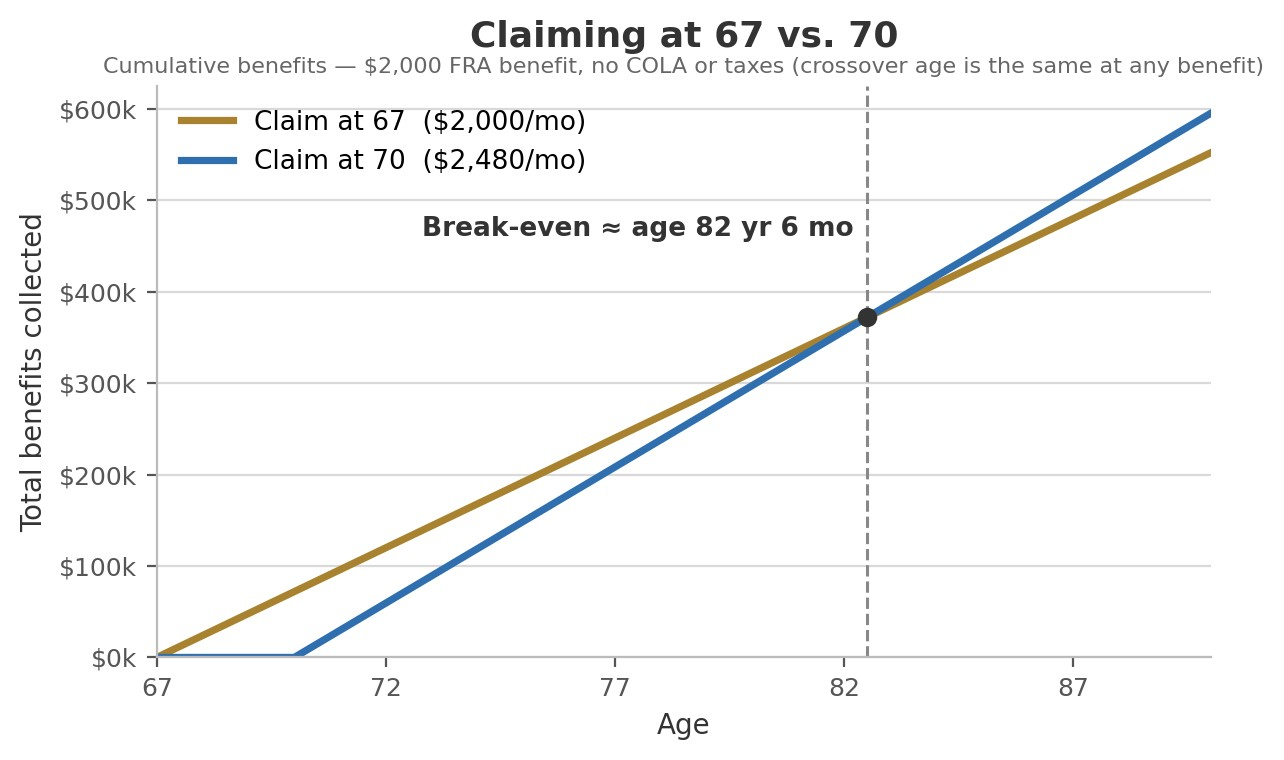
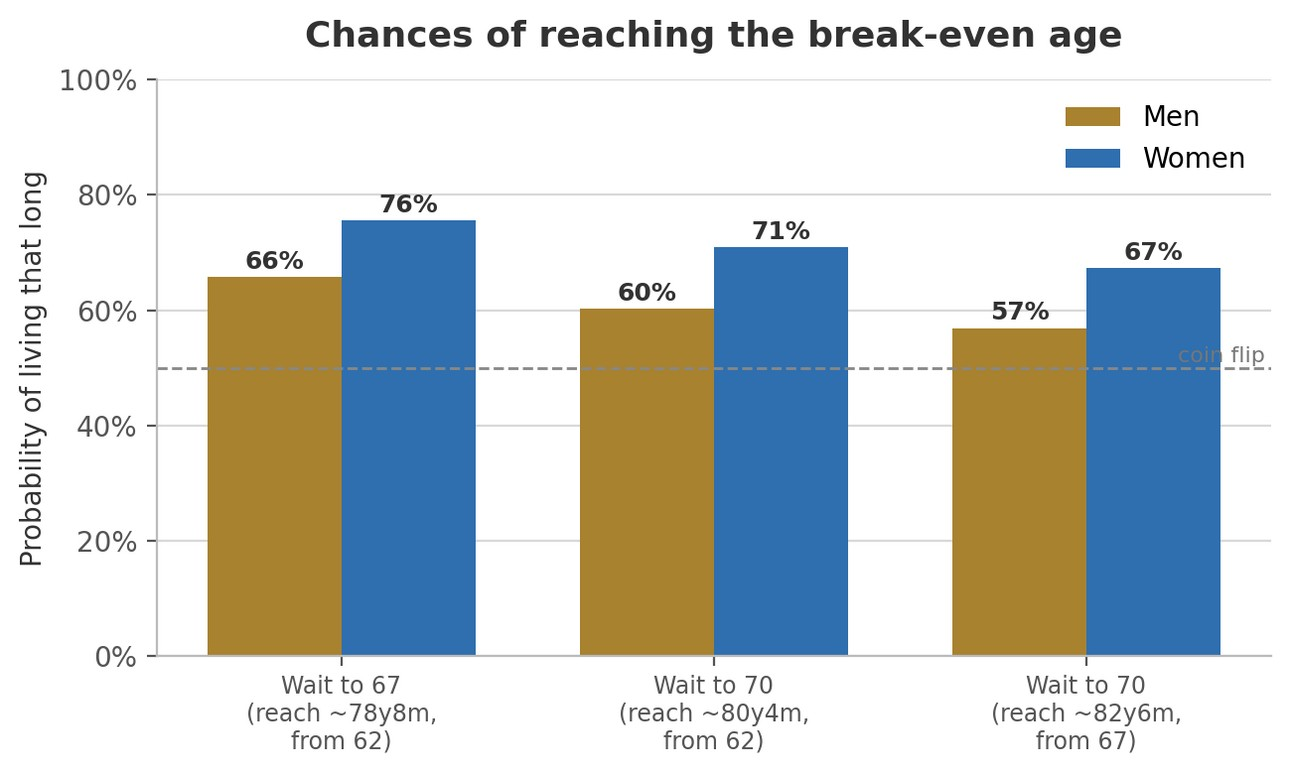
Chapter 6 — Medicare
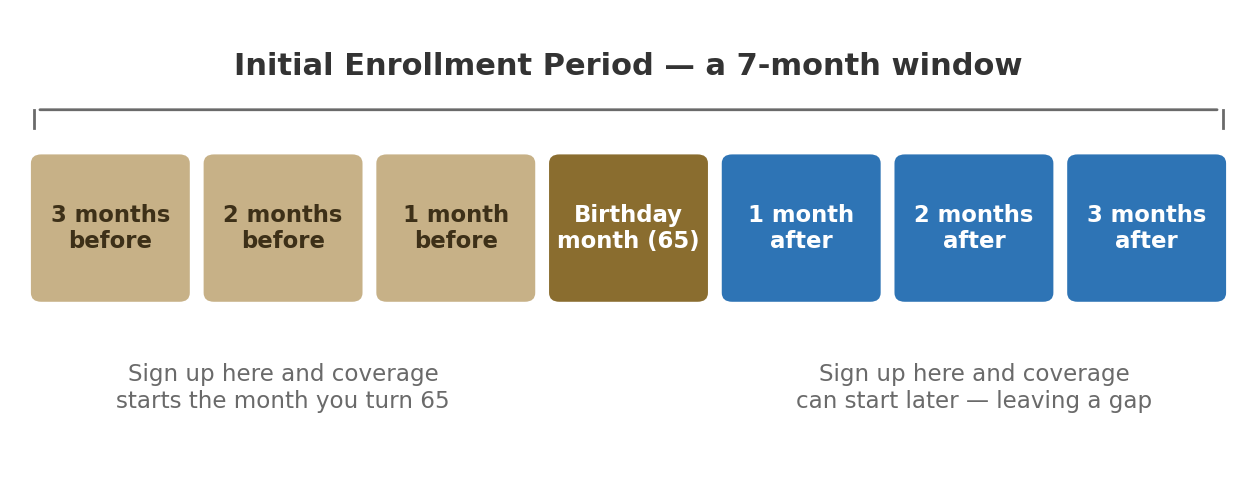
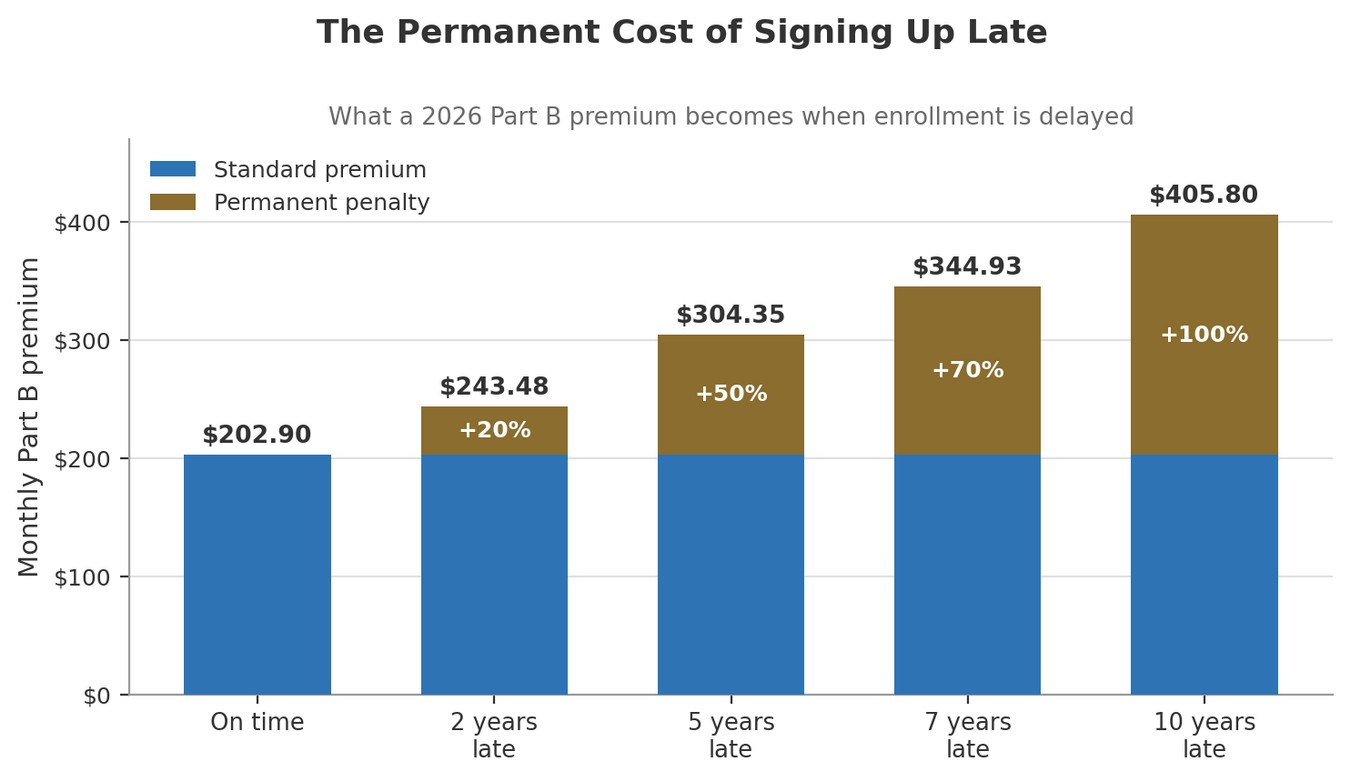
Chapter 10 — Roth Conversions
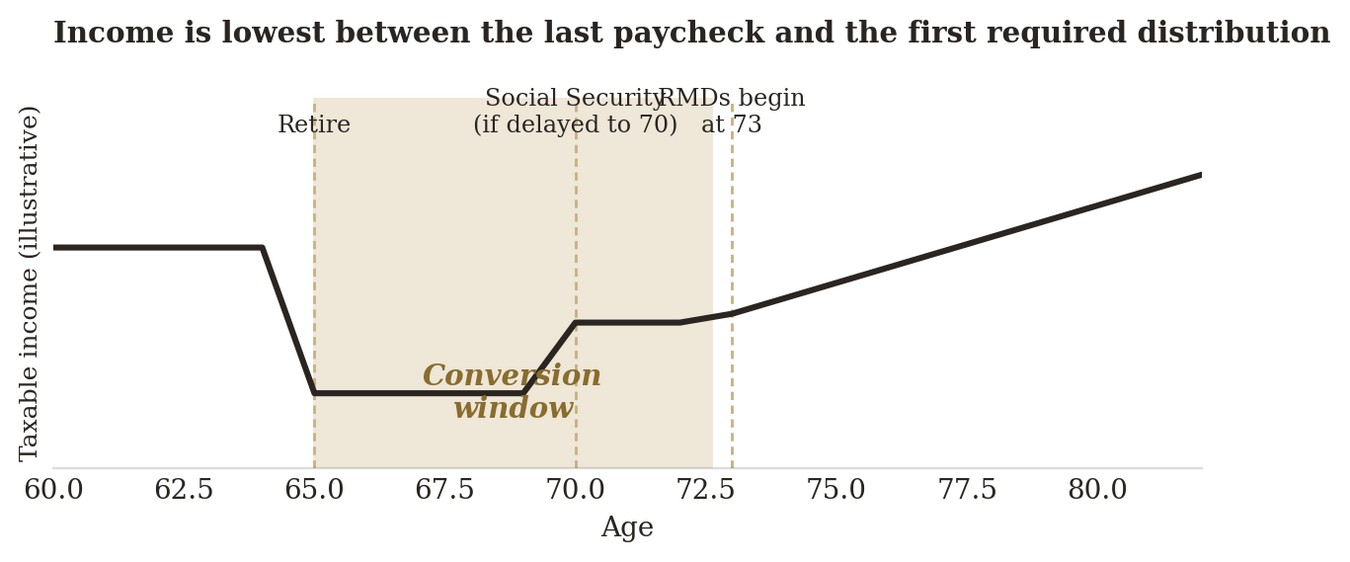
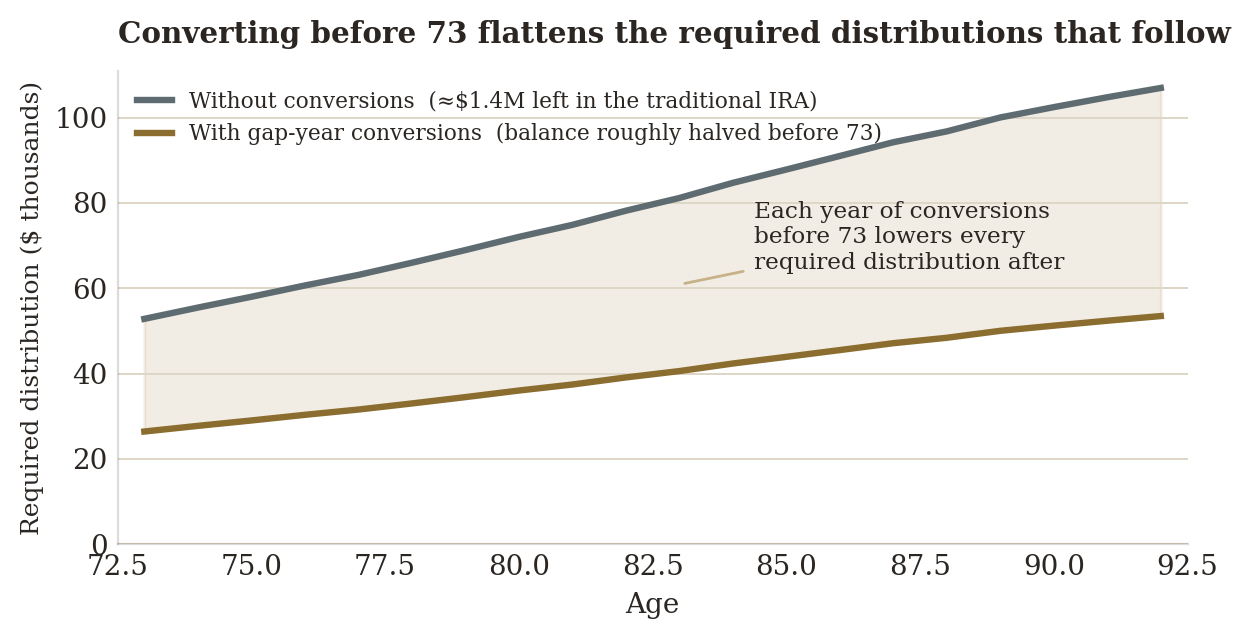
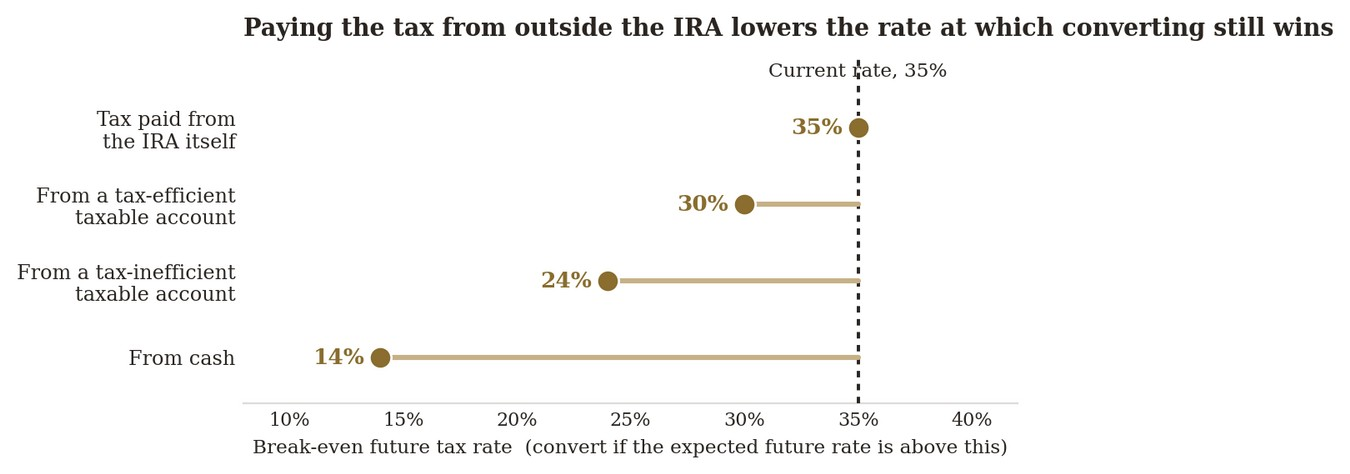
Chapter 11 — A Bond Alternative
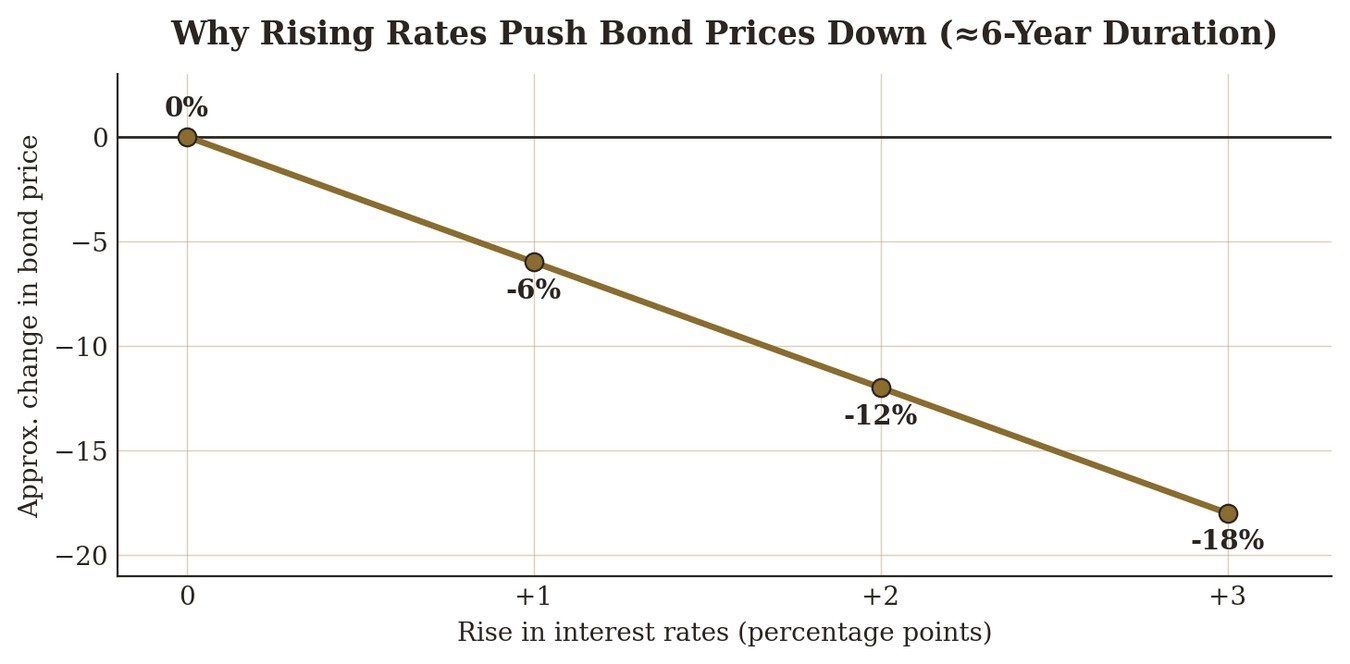
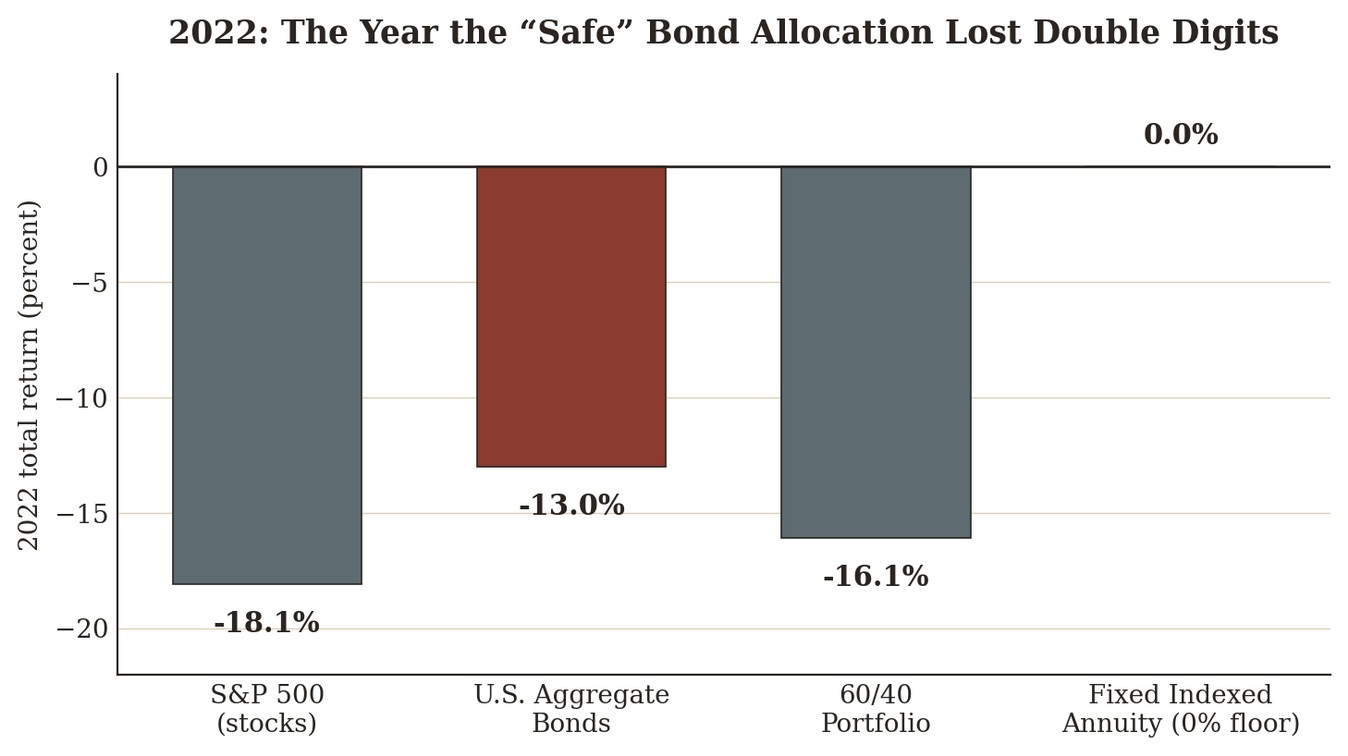
Chapter 12 — Fixed Indexed Annuities
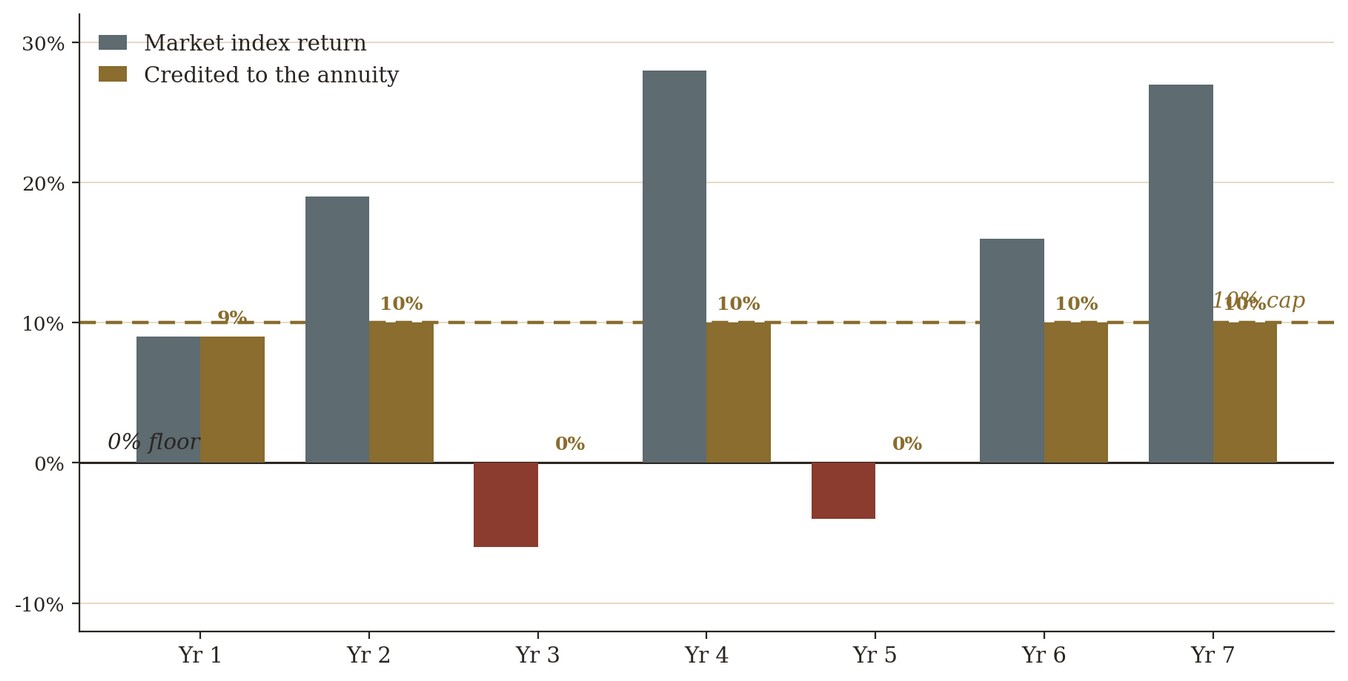
Chapter 13 — Indexed Universal Life
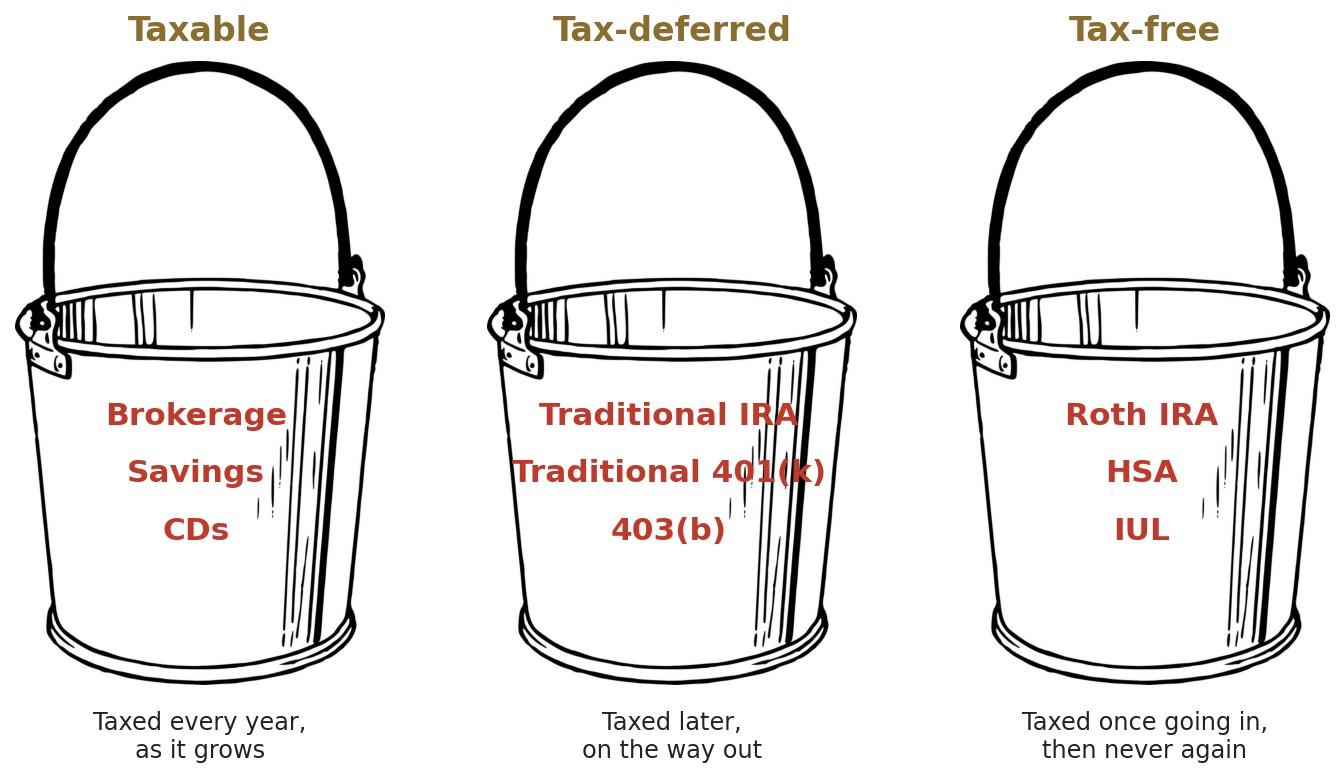
Chapter 14 — Tax Mitigation
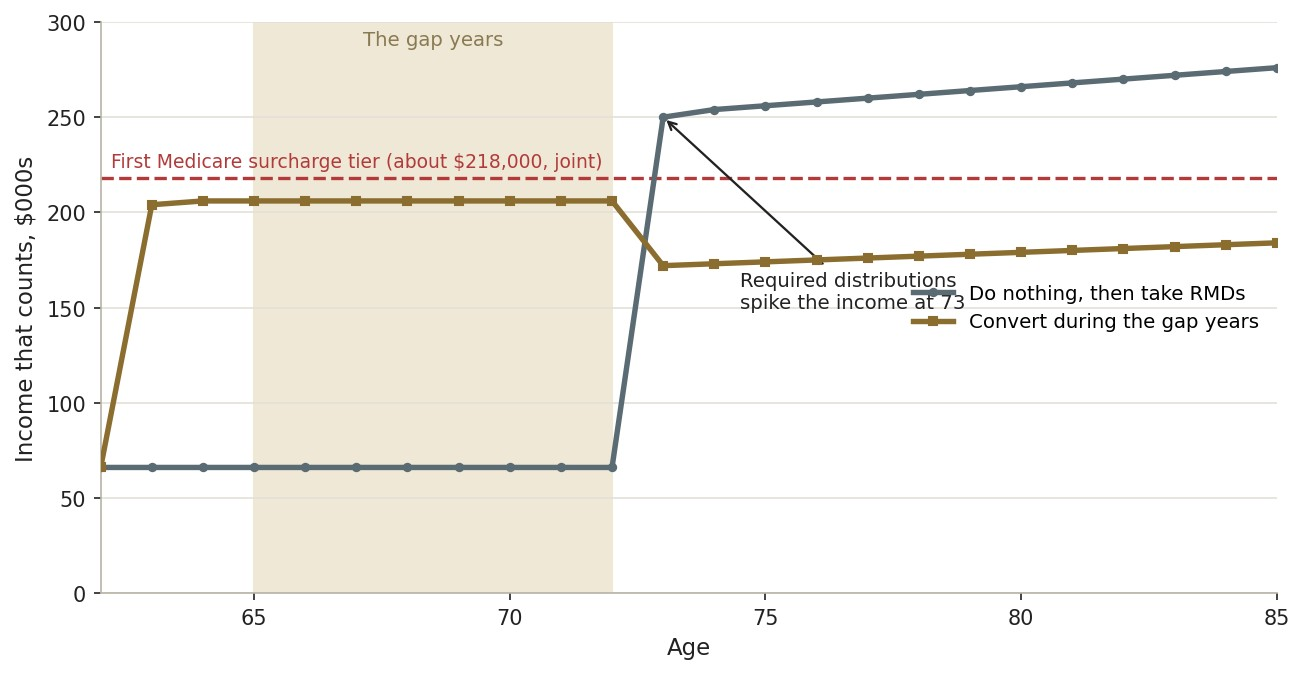
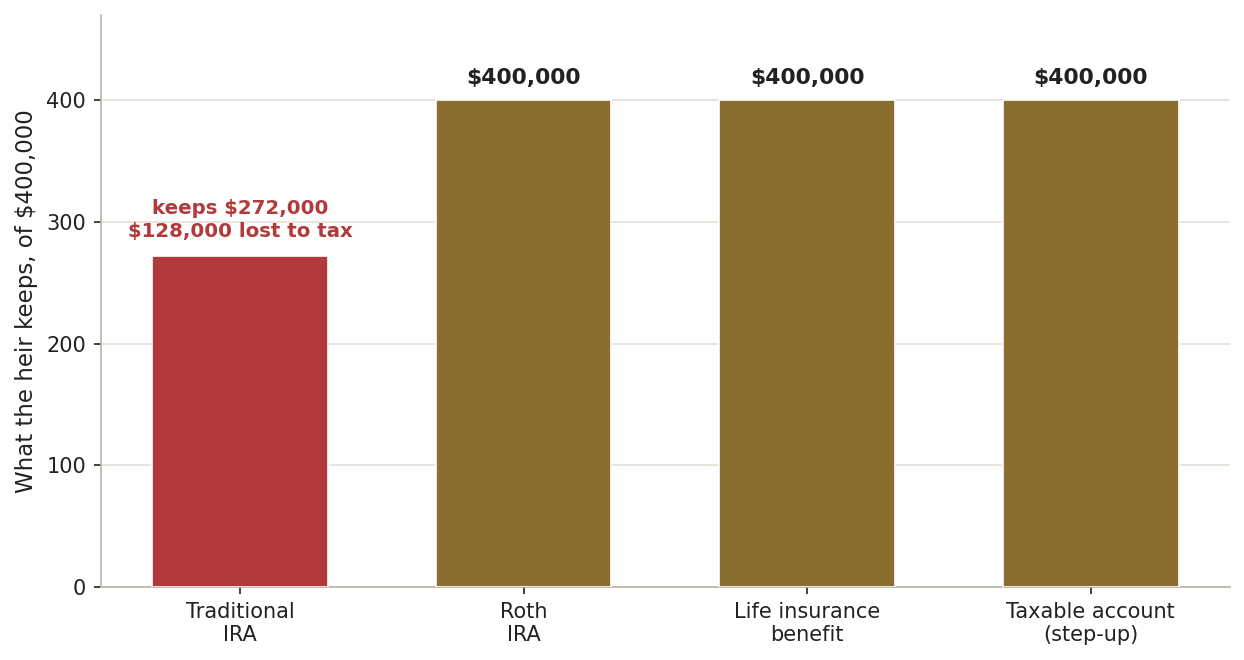
Chapter 15 — Generational Wealth Transfer
Tables
All 27 tables from the book, in chapter order.
Chapter 2
Scenario A — strong returns early, weak returns late
| Year | Start of Year | Return | Withdrawal | Net Spendable |
|---|---|---|---|---|
| 1 | $2,000,000 | 5.78% | $200,000 | $200,000 |
| 2 | $1,904,040 | 18.59% | $200,000 | $200,000 |
| 3 | $2,020,821 | 31.16% | $200,000 | $200,000 |
| 4 | $2,388,189 | 6.08% | $200,000 | $200,000 |
| 5 | $2,321,231 | 27.04% | $200,000 | $200,000 |
| 6 | $2,694,902 | 15.55% | $200,000 | $200,000 |
| 7 | $2,882,983 | (4.64%) | $200,000 | $200,000 |
| 8 | $2,558,492 | 31.65% | $200,000 | $200,000 |
| 9 | $3,104,955 | 18.53% | $200,000 | $200,000 |
| 10 | $3,443,243 | 6.59% | $200,000 | $200,000 |
| 11 | $3,456,973 | (7.03%) | $200,000 | $200,000 |
| 12 | $3,028,008 | 23.72% | $200,000 | $200,000 |
| 13 | $3,498,811 | 36.90% | $200,000 | $200,000 |
| 14 | $4,516,072 | (25.95%) | $200,000 | $200,000 |
| 15 | $3,196,051 | (14.42%) | $200,000 | $200,000 |
| TOTAL | $2,564,021 | 11.31% avg | $3,000,000 | $3,000,000 |
Scenario B — weak returns early, strong returns late
| Year | Start of Year | Return | Withdrawal | Net Spendable |
|---|---|---|---|---|
| 1 | $2,000,000 | (14.42%) | $200,000 | $200,000 |
| 2 | $1,540,483 | (25.95%) | $200,000 | $200,000 |
| 3 | $992,686 | 36.90% | $200,000 | $200,000 |
| 4 | $1,085,202 | 23.72% | $200,000 | $200,000 |
| 5 | $1,095,142 | (7.03%) | $200,000 | $200,000 |
| 6 | $832,251 | 6.59% | $200,000 | $200,000 |
| 7 | $673,935 | 18.53% | $200,000 | $200,000 |
| 8 | $561,760 | 31.65% | $200,000 | $200,000 |
| 9 | $476,246 | (4.64%) | $200,000 | $200,000 |
| 10 | $263,427 | 15.55% | $200,000 | $200,000 |
| 11 | $73,290 | 27.04% | $73,290 | $73,290 |
| 12 | $0 | 6.08% | $0 | $0 |
| 13 | $0 | 31.16% | $0 | $0 |
| 14 | $0 | 18.59% | $0 | $0 |
| 15 | $0 | 5.78% | $0 | $0 |
| TOTAL | $0 | 11.31% avg | $2,073,290 | $2,073,290 |
Chapter 3
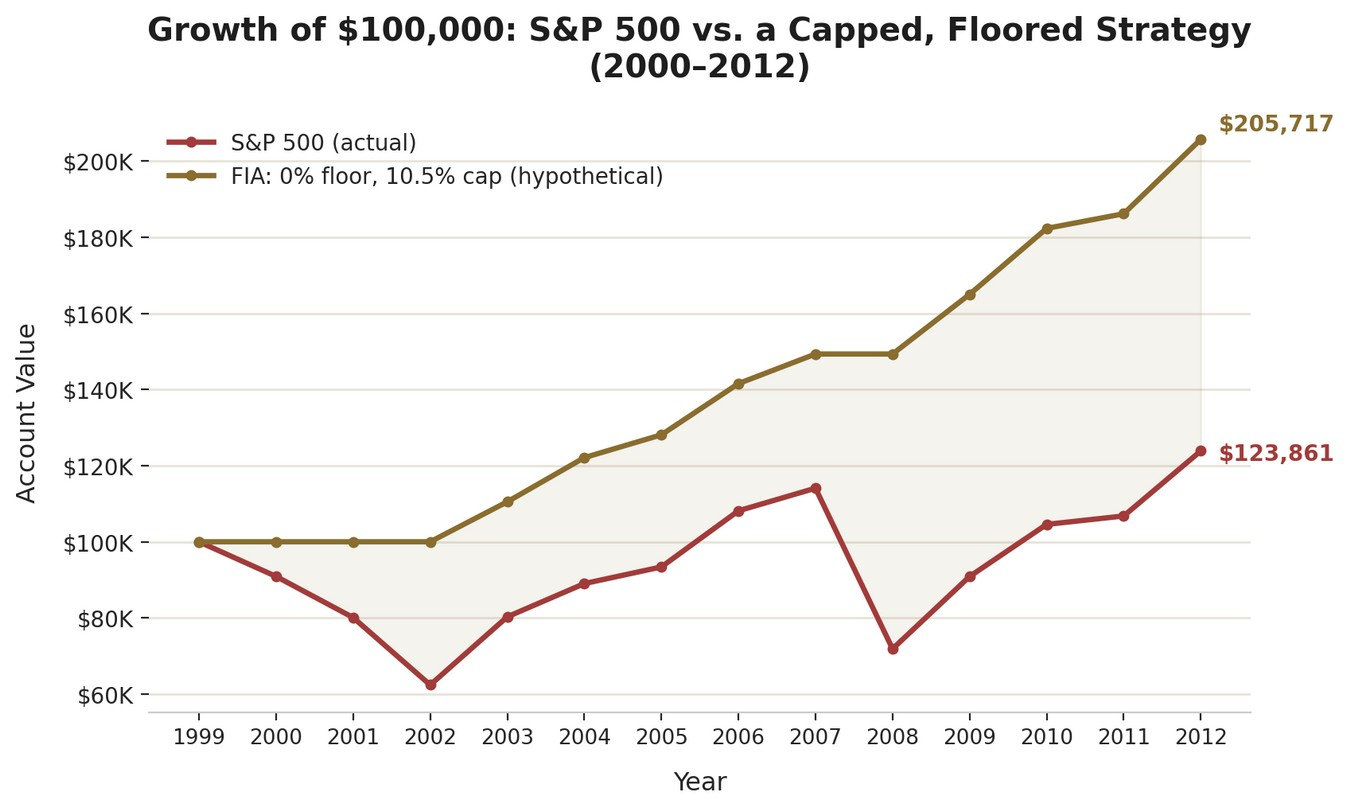
$100,000 invested 2000–2012: S&P 500 vs. a 0% floor / 10.5% cap
| Year | S&P 500 | FIA Credit | S&P Cumulative | FIA Cumulative |
|---|---|---|---|---|
| 2000 | (9.10%) | 0.00% | (9.1%) | 0.0% |
| 2001 | (11.89%) | 0.00% | (19.9%) | 0.0% |
| 2002 | (22.10%) | 0.00% | (37.6%) | 0.0% |
| 2003 | +28.68% | +10.50% | (19.7%) | +10.5% |
| 2004 | +10.88% | +10.50% | (11.0%) | +22.1% |
| 2005 | +4.91% | +4.91% | (6.6%) | +28.1% |
| 2006 | +15.79% | +10.50% | +8.1% | +41.5% |
| 2007 | +5.49% | +5.49% | +14.1% | +49.3% |
| 2008 | (37.00%) | 0.00% | (28.1%) | +49.3% |
| 2009 | +26.46% | +10.50% | (9.1%) | +65.0% |
| 2010 | +15.06% | +10.50% | +4.6% | +82.3% |
| 2011 | +2.11% | +2.11% | +6.8% | +86.2% |
| 2012 | +16.00% | +10.50% | +23.9% | +105.7% |
| TOTAL | — | — | $123,861 | $205,717 |
Three pieces, each with a different job
| Piece | When It’s Used | What It Holds | Job |
|---|---|---|---|
| Emergency Fund | Immediate | Cash, high-yield savings | Cover the unexpected: repairs, medical bills, surprises |
| Volatility Buffer | Ongoing | Fixed indexed annuity, 0% floor | Absorb down-market years without loss; never sold at a loss |
| Growth Portfolio | Long-term | Diversified stocks and bonds | Growth engine; replenishes the buffer in good years |
Chapter 4
Full retirement age by birth year
| Birth Year | Full Retirement Age |
|---|---|
| 1943–1954 | 66 |
| 1955 | 66 and 2 months |
| 1956 | 66 and 4 months |
| 1957 | 66 and 6 months |
| 1958 | 66 and 8 months |
| 1959 | 66 and 10 months |
| 1960 or later | 67 |
Chapter 5
Monthly benefit by the age benefits begin
| Age benefits begin | % of full benefit | 2026 max monthly |
|---|---|---|
| 62 | 70% | $2,969 |
| Full retirement age (67) | 100% | $4,152 |
| 70 | 124% | $5,181 |
Break-even ages and the cumulative difference by 90
| Decision | Break-even | Odds (M/W) | +$ by 90, $2k | +$ by 90, $4k |
|---|---|---|---|---|
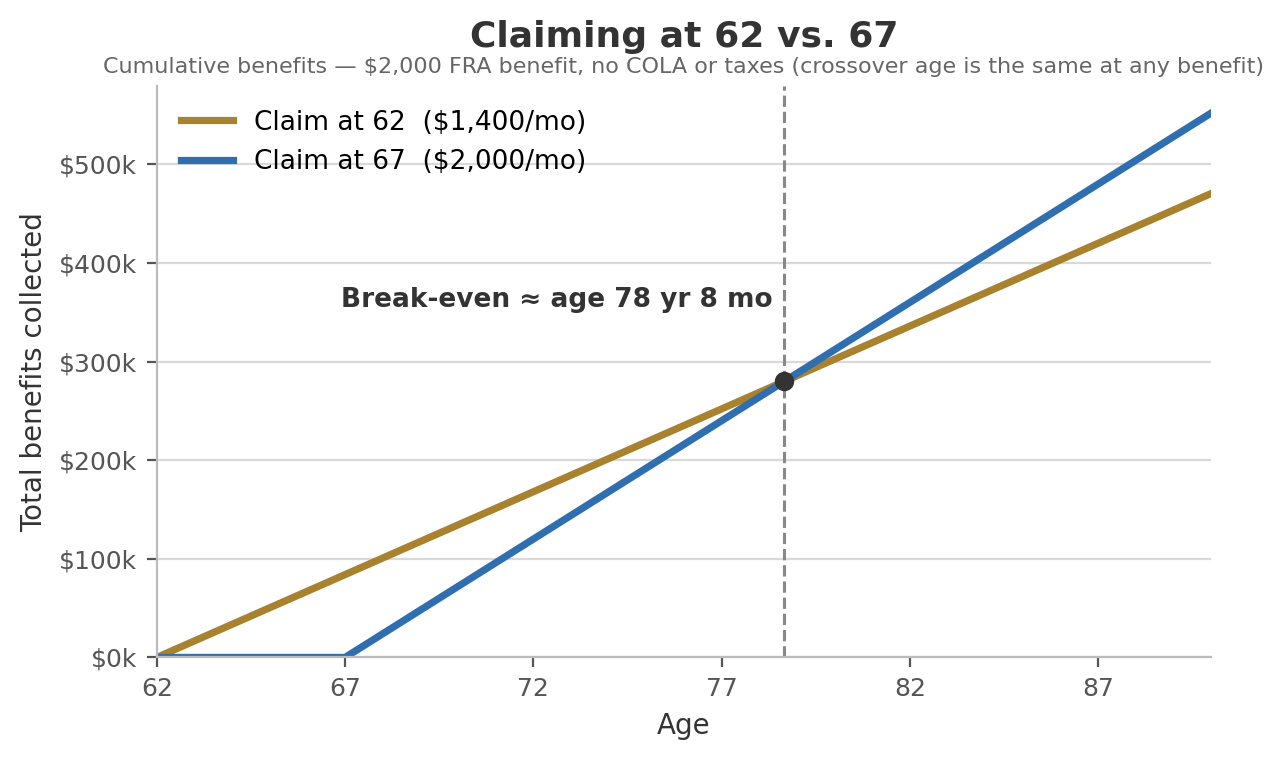
| Wait to 67 (vs 62) | ~78y 8m | 66/76% | +$81,600 | +$163,200 |
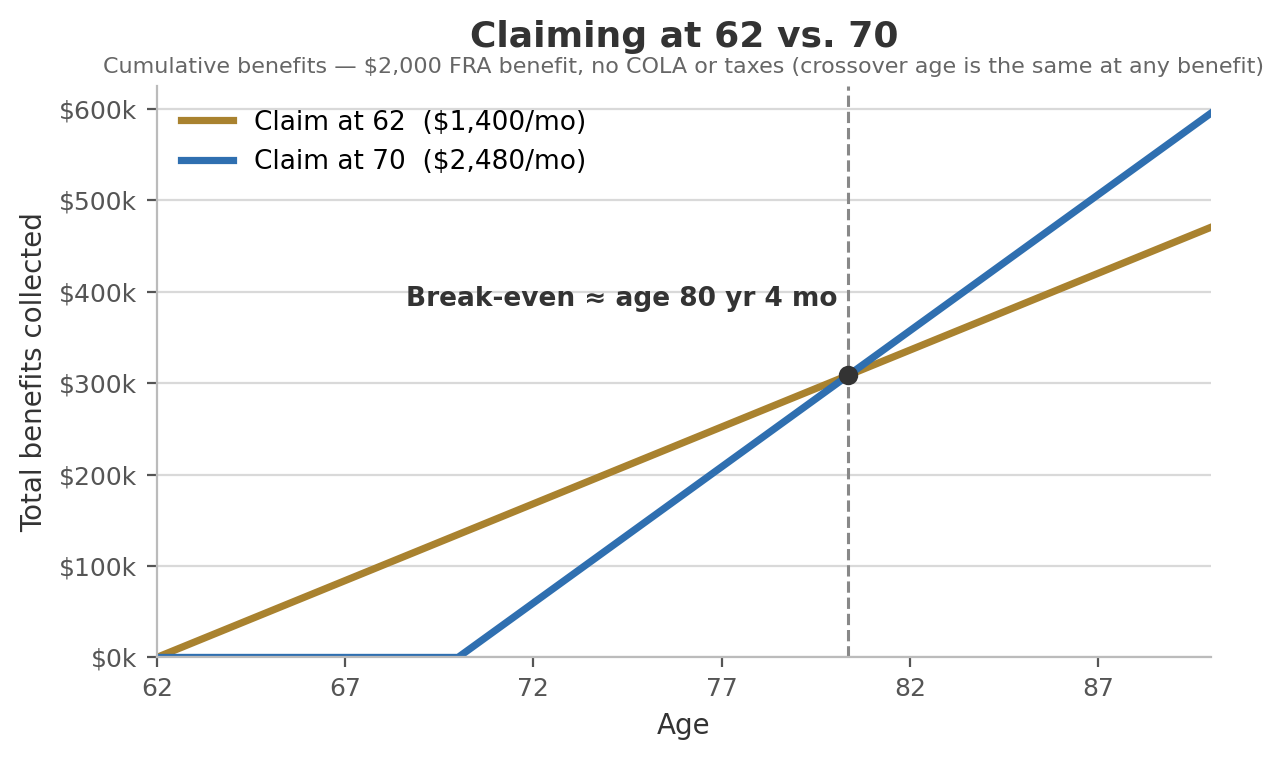
| Wait to 70 (vs 62) | ~80y 4m | 60/71% | +$124,800 | +$249,600 |
| Wait to 70 (vs 67) | ~82y 6m | 57/67% | +$43,200 | +$86,400 |
Chapter 6
The four parts of Medicare
| Part | What it covers | Who runs it | What it costs in 2026 |
|---|---|---|---|
| A | Hospital insurance: inpatient stays, skilled nursing after a hospital stay, hospice, some home health | Federal government | Premium-free for most (40+ work quarters); $1,736 hospital deductible per benefit period |
| B | Medical insurance: doctor visits, outpatient care, lab work, preventive care, equipment | Federal government | $202.90/month standard premium; $283 annual deductible; then 20% of most costs, with no cap |
| C | Medicare Advantage: an all-in-one private plan bundling A, B, and usually D, often with extras | Private insurers (Medicare-approved) | Varies; many plans add $0 beyond the Part B premium; networks and copays apply |
| D | Prescription drug coverage | Private insurers (Medicare-approved) | Varies widely by plan; many under $50/month, some $0 |
Original Medicare vs. Medicare Advantage
| Original Medicare + Medigap | Medicare Advantage | |
|---|---|---|
| Monthly cost | Higher: Part B premium plus a Medigap premium plus a Part D premium | Lower: often just the Part B premium; many plans add $0 |
| Doctors and hospitals | Any provider in the U.S. that accepts Medicare; no networks | A network of providers; out-of-network costs more or isn’t covered |
| Referrals and approvals | None | Often required, especially in HMOs |
| Out-of-pocket cap | Medigap keeps costs small and predictable; little gets through | A hard annual cap ($9,250 max in-network in 2026; often lower) |
| Extra benefits | Not included; bought separately | Dental, vision, hearing often bundled in |
| Prescription drugs | A separate Part D plan | Usually built in |
| Switching later | Can be denied for health reasons after the initial window | Can change every year during open enrollment |
| Best for | Predictability, travel, and freedom of choice | Lower premiums, extra benefits, comfort with a network |
Chapter 7
The Part D phases in 2026
| Phase | What the enrollee pays | 2026 figures |
|---|---|---|
| Deductible | Full negotiated price for covered drugs until the plan’s deductible is met | Up to $615; many plans set it lower or at $0 |
| Initial coverage | 25% of the cost of covered drugs (copay or coinsurance) | Continues until out-of-pocket reaches the annual cap |
| Catastrophic | $0 for covered Part D drugs for the rest of the calendar year | Begins once out-of-pocket reaches $2,100 |
Part D at a glance, 2026
| Item | 2026 |
|---|---|
| Annual out-of-pocket cap | $2,100, then $0 for covered Part D drugs the rest of the year |
| Maximum plan deductible | $615; plans may set it lower or at $0 |
| National base beneficiary premium | $38.99, a benchmark for penalties and subsidies, not a typical premium |
| Insulin, per month’s supply | No more than the lowest of $35, 25% of the negotiated price, or 25% of Medicare’s Maximum Fair Price; no deductible applies |
| Recommended adult vaccines | $0 cost-sharing, including the shingles vaccine |
| Late-enrollment penalty | 1% of $38.99 per full uncovered month, added to the premium permanently; triggered by a 63-day gap without creditable coverage |
Chapter 8
IRMAA: income thresholds and the surcharge they trigger
| Income (single filer) | Income (married, joint) | Monthly Part B | Part D surcharge |
|---|---|---|---|
| Up to $109,000 | Up to $218,000 | $202.90 | None |
| $109,001–$137,000 | $218,001–$274,000 | $284.10 | +$14.50 |
| $137,001–$171,000 | $274,001–$342,000 | $405.80 | +$37.50 |
| $171,001–$205,000 | $342,001–$410,000 | $527.50 | +$60.40 |
| $205,001–$500,000 | $410,001–$750,000 | $649.20 | +$83.30 |
| Above $500,000 | Above $750,000 | $689.90 | +$91.00 |
What Medicare does and does not cover
| Care or benefit | Original Medicare | Medigap | Medicare Advantage |
|---|---|---|---|
| Routine dental | Not covered | Not covered | Often a limited allowance |
| Routine vision (exams, glasses) | Not covered | Not covered | Often a limited allowance |
| Hearing exams and aids | Not covered | Not covered | Often a limited allowance |
| Routine foot care (podiatry) | Not covered (routine) | Not covered | Sometimes included |
| Annual physical exam | Not covered | Not covered | Sometimes included |
| Long-term / custodial care | Not covered | Not covered | Not covered |
| Outpatient prescription drugs | Not covered | Not covered | Usually included |
| Care outside the United States | Not covered | Emergency (some plans) | Emergencies only |
| Annual out-of-pocket limit | No annual limit | Limits exposure | Annual cap |
Long-term care costs, 2026 and projected 2046
| Type of care | 2026 monthly (median) | Projected 2046 |
|---|---|---|
| In-home care (home health aide) | $6,673 | ~$14,600 |
| Assisted living | $6,200 | ~$13,600 |
| Nursing home, private room | $10,800 | ~$23,700 |
Chapter 9
Required minimum distribution divisors
| Age | Distribution period (divisor) | RMD as % of balance |
|---|---|---|
| 73 | 26.5 | 3.8% |
| 75 | 24.6 | 4.1% |
| 80 | 20.2 | 5.0% |
| 85 | 16.0 | 6.3% |
| 90 | 12.2 | 8.2% |
| 95 | 8.9 | 11.2% |
Chapter 10
2026 top of each bracket
| Top rate on income up to | Married, filing jointly | Single filer |
|---|---|---|
| 10% | $24,800 | $12,400 |
| 12% | $100,800 | $50,400 |
| 22% | $211,400 | $105,700 |
| 24% | $403,550 | $201,775 |
Backdoor Roth vs. mega-backdoor Roth
| Backdoor Roth | Mega-backdoor Roth | |
|---|---|---|
| Who it fits | Earners above the Roth income limit | Employees whose 401(k) allows after-tax contributions |
| How it works | A non-deductible traditional IRA contribution, then a conversion | After-tax 401(k) contributions, then a conversion to Roth |
| 2026 ceiling | The $7,500 IRA contribution limit | Up to the $72,000 total plan limit, minus deferrals and match |
| Main catch | The pro-rata rule, if other pre-tax IRA money exists | The plan must allow both the contributions and the conversion |
Chapter 11
Bonds vs. a fixed indexed annuity
| Bonds and bond funds | Fixed indexed annuity | |
|---|---|---|
| Safety | Can lose value when rates rise, as 2022 showed | A 0% floor blocks market loss; backed by the insurer, not the FDIC |
| Liquidity | Sellable on any business day | About 10% a year withdrawable free; larger withdrawals charged during a 7-to-10-year surrender period |
| Return | A stated yield, lately about 3% to 5% | Index-linked and capped; 0% in a down year, often near 5% to 7% on average |
| Taxes | Interest taxed yearly in a taxable account | Grows tax-deferred until withdrawal |
| Cost | Many funds charge an annual expense ratio | Many carry no ongoing fee; riders cost extra |
Chapter 12
Crediting methods, side by side
| Crediting method | What it does | Index up 12% | Index down 6% |
|---|---|---|---|
| Cap of 10% | Credits the gain up to a ceiling | 10% | 0% |
| Participation of 60% | Credits a set share of the gain | 7.2% | 0% |
| Spread of 3% | Credits the gain minus a set amount | 9% | 0% |
What to ask about an annuity, and why it matters
| What to ask | Why it matters |
|---|---|
| Which crediting method, and at what cap, participation rate, or spread? | These set how much of an up year reaches the account. The opening rate is only a starting point. |
| How long is the opening rate guaranteed, and what is the guaranteed minimum? | A rate locked for a single year can reset much lower. The minimum is the true worst case. |
| What have the company’s renewal rates been over the past five to seven years? | Past renewals show whether the opening rate was bait or a lasting offer. |
| Which index, and is it the plain S&P 500 or a proprietary one? | Proprietary volatility-controlled indexes pair high participation rates with lower built-in returns, so the two numbers can mislead. |
| How long is the surrender period, and how do the schedule and market value adjustment work? | This is the money’s lockup. It should match cash the household will not need. |
| How much can be withdrawn free each year? | Usually about 10 percent. It sets everyday access and whether the contract can double as a buffer. |
| Which riders apply, which cost extra, and does any bonus carry strings? | Income riders run about 1 percent a year. A bonus is paid for elsewhere in the contract. |
| How financially strong is the issuing company? | The guarantee rests on its ability to pay claims, backed only secondarily by a state limit. |
Chapter 13
When indexed universal life fits, and when it does not
| Indexed universal life fits when | A simpler tool fits better when |
|---|---|
| The goal is a permanent, income-tax-free transfer to the next generation | The need is temporary protection during the working years, which term covers cheaply |
| The cheaper tax-free accounts, Roth, workplace Roth, and HSA, are already full | Roth, workplace, and HSA room still sits unused |
| A long horizon is available, whether the insured is the buyer or a young child or grandchild | Neither the buyer nor a younger insured has decades for the cash value to build |
| The owner will fund the policy generously and mind it for years | There is no desire to fund and manage a long-term contract |
| Tax-free retirement income matters, especially at high or rising tax rates | Current and expected tax rates are low enough that the tax-free feature adds little benefit |
Chapter 14
Three phases of retirement, and the move in each
| Phase | Typical ages | What has and has not started | The main move |
|---|---|---|---|
| Before Medicare | Up to 64 | No required distributions; often low income; individual-market health coverage in play | Convert or realize gains in a low bracket, watching the subsidy cliff |
| The gap years | 65 to 72 | On Medicare, so surcharges now apply; Social Security perhaps delayed; distributions not yet forced | Fill a bracket with conversions, staying under the next surcharge tier |
| Required distributions | 73 and up | Distributions force income; Social Security is on; the survivor’s higher rates loom | Use charitable distributions, draw the order deliberately, live on a base already lowered |
The thresholds a conversion is filled up to
| Threshold (2026) | Roughly where it sits | Why it matters |
|---|---|---|
| Top of the 12% bracket | About $100,800 taxable, joint | Income above it is taxed at 22 percent and can begin taxing long-term gains |
| Top of the 22% and 24% brackets | About $211,400 and $403,550 taxable, joint | Common ceilings a conversion is filled up to, not past |
| Zero-rate capital gains | Up to about $98,900 taxable, joint | Below it, long-term gains and qualified dividends are taxed at zero |
| First Medicare surcharge tier | $218,000 joint, or $109,000 single, on income from two years earlier | One dollar over adds the full surcharge for the year |
| Net investment income tax | $250,000, joint | An extra 3.8 percent on investment income above the line |
| Health-subsidy cliff, before 65 | Around four times the poverty line | Where individual-market premium help can drop sharply |
Chapter 15
What the heir owes, by account type
| Account left to heirs | What the heir owes in tax | The catch, or the gift |
|---|---|---|
| Traditional IRA or 401(k) | Ordinary income tax on every dollar | Must be emptied within ten years, often in the heir’s peak earning years |
| Roth IRA | Nothing, if the account was open five years | Still emptied within ten years, but the growth stays tax-free |
| Life insurance death benefit | Nothing | Passes income-tax-free, outside probate, to the named beneficiary |
| Taxable brokerage account | Tax only on growth after the date of death | The step-up erases the gain built up during the owner’s life |
| Cash and bank accounts | Nothing on the principal | Already taxed; it simply passes to the heir |
The ten-year clock, by type of heir
| The heir | How long to withdraw | What it means |
|---|---|---|
| A surviving spouse | Can treat the account as their own | The most flexible option; withdrawals can wait for years |
| An eligible designated beneficiary | Over their own lifetime | A minor child of the owner, a disabled or chronically ill heir, or one not more than ten years younger |
| Most other heirs | Within ten years | The standard rule for adult children and other non-spouse heirs |
| A successor beneficiary | Only the time left on the first clock | Inherits an already-inherited account, with no fresh ten years |
Chapter 16
The four layers of a plan
| The layer | The task | The fear it answers |
|---|---|---|
| One: the floor | Cover the essential bills with income that cannot run out, from Social Security, a pension, and if needed a lifetime-income product | Running out; market loss |
| Two: healthcare | Enroll in Medicare on time, choose the path with an eye on the later lock-in, and plan around the income surcharge | A Medicare surprise |
| Three: the tax years | Coordinate the three buckets, convert in the gap years, and draw down in a low-rate order | Paying too much tax |
| Four: the tail and the transfer | Plan for long-term care, and arrange a tax-efficient legacy with current documents | Running out late in life; protecting heirs |
The yearly review
| When | What to check |
|---|---|
| Each fall, October 15 to December 7 | Re-shop the Medicare drug and Advantage coverage during open enrollment, since plans change every year |
| Before year-end | Size the year’s Roth conversion to a bracket and under the next surcharge tier, take any required distribution, and give from the IRA if making charitable gifts |
| After any large life or income change | Re-check the plan; a marriage, a death, a windfall, or a new law can move several layers at once |
| Once a year, in any case | Confirm the beneficiary form on every account still names the right people |
Cast of characters
All six are invented. The situations are not.
Dave and Mary Thompson, 64 and 61
Dave and Mary are the book’s anchor couple, and they appear more than anyone else. Dave still picks up part-time consulting work; Mary retired from teaching last year and is still getting used to the rhythm of it. They’ve done most things right (they saved, they paid off the house, they raised two kids who turned out fine), and now they’re facing the same question almost every couple their age eventually asks: how to turn what they’ve built into income that lasts? Dave is also five years into managing an IRA he inherited from his father, who passed away at 79, already several years into his own required withdrawals, which means Dave has been taking annual distributions of his own, with five years left before the account must be fully emptied. Mary also built up a health savings account during her working years, a detail that matters once Medicare enters the picture. To keep their numbers straight: Dave has a traditional IRA of one hundred thousand dollars. Mary has a Roth IRA of one hundred fifty thousand, a health savings account of twenty-eight thousand, and a pension. Their home in Staunton, Virginia is paid off. Their children are Kevin and Allison. And the account he inherited from his father holds sixty thousand dollars.
Linda Castellano, 58
Linda spent thirty years in healthcare administration and built a solid 401(k) along the way: a mix of traditional contributions, a smaller Roth portion she started later in her career, and years of employer match, which by law always lands in the traditional, not-yet-taxed bucket. Divorced, with one grown daughter, Maya, she’s planning retirement the way she’s done most things: on her own. Linda’s chapters look different from the Thompsons’: there’s no spouse to coordinate Social Security with, no second income to fall back on, and a sharper edge to the question of what happens if it’s just her for the next thirty years. Linda also carries an inherited IRA with a more complicated history. Her maternal grandmother passed away eight years ago, already taking her own required distributions, and Linda’s mother inherited the account as a non-spouse heir, which started a 10-year distribution clock with annual withdrawals required along the way. When her mother passed away two years ago, Linda inherited the same account as what’s known as a successor beneficiary, which means she didn’t get a fresh 10-year window of her own. She’s now racing the final two years of her mother’s original clock, a useful and often misunderstood example later in the book. Her numbers: a four oh one k holding four hundred twenty thousand dollars in total, of which three hundred forty thousand is traditional money and employer match, and eighty thousand is Roth. A taxable brokerage account of thirty-five thousand. A condo with a small mortgage remaining. One daughter, Maya.
Robert and Susan Whitfield, 67 and 65
Robert sold the small business he spent two decades building; Susan retired from a corporate VP role not long after. Between the two of them, they’ve accumulated more than most (a sizable IRA, a taxable brokerage account, a vacation home on the Outer Banks), which means they also have more decisions to make, and more at stake if they get them wrong. The Whitfields show up most often in the later chapters, where Roth conversions, annuities, and legacy planning actually have room to matter. Their numbers: a traditional IRA of one point two million dollars. A taxable brokerage account of four hundred thousand. Susan’s former four oh one k, holding two hundred thousand. A primary home and a paid-off vacation property. And three adult children.
Walter Higgins, 84
Walter is further down the road than the rest of the cast, and that’s exactly the point. A retired postal worker and steady saver his whole life, he retired in 2008 at 66, right as the financial crisis hit, and watched the downturn do enough damage to his portfolio that he went back to work for a few more years to recover. Once he was working again, he suspended his Social Security benefit rather than keep collecting it, letting it grow through delayed retirement credits until he restarted it at 69, at a noticeably higher monthly amount than what he’d locked in at 66. He’s been taking required minimum distributions for years now, not reading about them, living them. His wife, Carol, passed three years ago; his daughter Patricia has started helping manage the details. Walter is also Susan Whitfield’s father, which means his story and the Whitfields’ will eventually intersect, a connection that pays off later in the book. His numbers: a traditional IRA of three hundred forty thousand dollars, already in required distribution. A survivor pension from Carol’s former employer. He has been on a Medicare Advantage plan since sixty-five, and is now managing a heart condition. His home is paid off. His daughter Patricia holds financial power of attorney.
Glossary
31 terms used in the book.
Adjusted gross income (AGI) — A person’s total income minus certain adjustments, calculated on the federal tax return. It is the starting point for many other figures, including the income measures that drive Medicare surcharges and health subsidies.
Annual gift exclusion — The amount one person can give to another in a year without using any lifetime gift and estate exemption or filing a gift tax return. It was $19,000 per recipient in 2026.
Cap — In a fixed indexed annuity or indexed universal life policy, the highest interest rate that can be credited in a given period, no matter how much the underlying index rises.
Cost of insurance — The internal charge inside a permanent life insurance policy that pays for the death benefit. It rises as the insured ages and is deducted whether the policy’s index gains or sits flat.
Delayed retirement credits — The increase, about 8 percent for each year, that a Social Security benefit earns for each year a person waits to claim past full retirement age, up to age seventy.
Eligible designated beneficiary — A category of heir who may stretch withdrawals from an inherited retirement account over a lifetime rather than emptying it within ten years. It includes a surviving spouse, a minor child of the owner, a disabled or chronically ill heir, and an heir not more than ten years younger than the owner.
Fixed indexed annuity — An insurance contract whose interest is tied to a market index, with a floor that prevents a loss in a down year and a cap or other limit on the gain in an up year. It is often used as a volatility buffer.
Full retirement age — The age at which a person can claim an unreduced Social Security benefit, ranging from sixty-six to sixty-seven depending on the year of birth.
Guaranteed minimum — The floor an annuity contract promises, such as a minimum interest rate or a minimum lifetime income, regardless of how the index performs.
Indexed universal life — A permanent life insurance policy whose cash value earns interest tied to a market index, with a floor and a cap, and whose death benefit passes to heirs free of income tax.
IRMAA — The income-related monthly adjustment amount, a surcharge added to Medicare Part B and Part D premiums for higher-income beneficiaries, based on income from a tax return two years earlier.
Market value adjustment — An increase or decrease applied to a larger-than-allowed annuity withdrawal during the surrender period, reflecting how interest rates have moved since the contract began.
Medicare Advantage — A privately run alternative to Original Medicare that bundles hospital, medical, and usually drug coverage into one plan, often with a lower premium but a fixed network and a later limit on switching to a supplement.
Medigap — A Medicare Supplement policy that pays many of the out-of-pocket costs Original Medicare leaves behind. Outside an early enrollment window, switching into one can require medical underwriting.
Modified adjusted gross income (MAGI) — A person’s adjusted gross income with certain items added back. Different programs define it slightly differently; the version used for Medicare surcharges adds back tax-exempt interest.
Modified endowment contract (MEC) — A life insurance policy funded so quickly that the tax code reclassifies it, removing the tax advantages of its withdrawals and loans. Careful funding keeps a policy under this line.
Multi-year guaranteed annuity (MYGA) — An annuity that pays a fixed interest rate for a set number of years, often used as an alternative to a certificate of deposit.
Participation rate — In an indexed product, the share of an index’s gain that is credited to the account, such as 80 percent of the index’s rise.
Point-to-point crediting — A method that measures an index’s change from the start of a period to its end, ignoring the movement in between, to decide the interest credited.
Probate — The court process that validates a will and settles an estate. It can take months and is a matter of public record; assets that pass by beneficiary designation skip it.
Qualified charitable distribution (QCD) — A gift sent directly from a traditional IRA to a charity, available after age seventy and a half, that counts toward the required distribution but is left out of taxable income.
Required beginning date — The point at which required minimum distributions must start, generally April 1 of the year after a person reaches the required age.
Required minimum distribution (RMD) — The amount the law forces out of a traditional retirement account each year once the owner reaches the required age, currently seventy-three and rising to seventy-five for those born in 1960 or later.
Revocable living trust — An arrangement that holds assets during life and passes them at death without probate, while remaining changeable by the person who created it.
Roth conversion — Moving money from a traditional retirement account to a Roth account, paying income tax on the amount moved in exchange for tax-free growth and withdrawals afterward.
Spread — In an indexed product, an amount subtracted from the index’s gain before interest is credited, such as crediting the index’s rise minus 2 percent.
Step-up in basis — The reset of an asset’s cost to its value on the owner’s date of death, which erases the capital gain that built up during the owner’s life for the heirs who inherit it.
Successor beneficiary — The person who inherits a retirement account that had already been inherited once. A successor receives only the time left on the original ten-year clock, not a fresh ten years.
Surrender charge — A fee for withdrawing more than the allowed amount from an annuity during its early years, usually declining to zero by the end of the surrender period.
Tax buckets — A way of sorting savings by how they are taxed: taxable accounts, tax-deferred accounts such as a traditional IRA, and tax-free accounts such as a Roth.
Volatility buffer — A pool of money that does not fall when markets fall, drawn on during a downturn so that investments are not sold at a loss, giving the rest of a portfolio time to recover.
Sources
The dollar figures in this book come from the agencies that set them. Those numbers are revised every year, and the laws behind them can change at any time, so the most useful thing this section can do is point to the offices that publish the current figures. Any amount in these pages can then be checked against the year in which it is heard. The figures throughout are stated for 2026.
For Medicare, the Centers for Medicare and Medicaid Services publish the annual Medicare costs. Their yearly fact sheet on Medicare Parts A and B premiums and deductibles is the source for the Part B premium, the Part A and Part B deductibles, and the income-related surcharge tiers. The Part D figures, including the out-of-pocket cap, the maximum deductible, and the base beneficiary premium, come from the annual Part D redesign program instructions. Plan-level costs and the current-year basics are summarized for the public at medicare.gov.
For Social Security, the Social Security Administration publishes the annual benefit and earnings figures at ssa.gov. Its yearly cost-of-living adjustment fact sheet is the source for the earnings-test limits and the taxable maximum, and the retirement pages of its Benefits Planner explain the claiming ages, the delayed retirement credits, and how the earnings test is applied.
For federal income, capital gains, and estate taxes, the Internal Revenue Service publishes the annual inflation adjustments as a Revenue Procedure, summarized in a companion news release at irs.gov. That release is the source for the tax brackets, the standard deduction, the long-term capital gains thresholds, and the estate and gift exemption. A separate annual notice on retirement plan limits is the source for the contribution amounts.
For further reading, and for plain-language explanations that track these releases each year, the Tax Foundation is a reliable nonpartisan source on the tax figures, and the Medicare Rights Center and the Center for Medicare Advocacy are both reliable on Medicare. All three publish at their own websites, and a search on the organization’s name will find the current pages.
Every figure in this book should be confirmed against the current-year release before it is relied on. Where a number in these pages differs from an agency’s current figure, the agency’s figure governs.
Remarks attributed to named public figures are widely published statements, quoted to illustrate a point.
This material is educational and informational. It is not financial, tax, legal, investment, or insurance advice for any particular person. The figures are stated for 2026 and change frequently. Every household’s situation is different, and any figure or rule here should be confirmed against current sources, and against a qualified professional, before it is relied on.
Don’t Run Out © 2026 Jeff Batson. Audiobook narrated with a synthetic voice.